Transparent Technical Scopes & Illustrative CAD Cost Benchmarks
Understand contractor replacement square rates, emergency tarping mobilization, and diagnostic dossier packages prior to insurance adjuster settlement. Engineered for high-wind Prairie climate realities.
Illustrative estimates based on typical Southern Manitoba single-family residential architecture (bungalow & two-storey typologies). Final contractor quotes require on-site physical measurement, pitch verification, and forensic shingle pull analysis. We do not offer claim adjustment or legal adjudication.
Reflects synthetic high-tack ice/water shield, impact-resistant SBS shingles, and Manitoba cold-climate ventilation standards.
appropriately qualified Scoping & Field Restoration Tiers
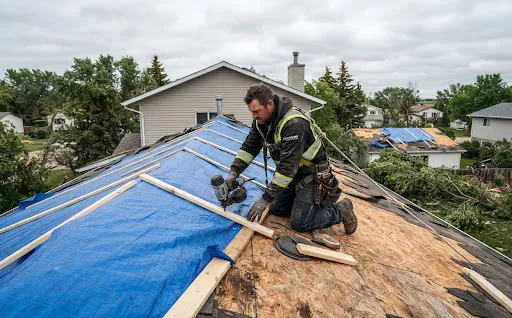
Emergency Weather Containment & Tarping
Rapid mitigation against secondary water intrusion during severe wind/hail events.
- check_circle Requested scheduling within Red River & Winnipeg metro zone
- check_circle Up to 400 sq.ft industrial-grade 12-mil poly reinforced tarp
- check_circle Non-penetrating 2x4 timber batten anchors along rafter lines
- check_circle Pre- and post-mitigation GPS timestamped evidence packet
Forensic Damage Dossier & Adjuster Scoping
Engineering-level hail and wind impact documentation before adjuster attendance.
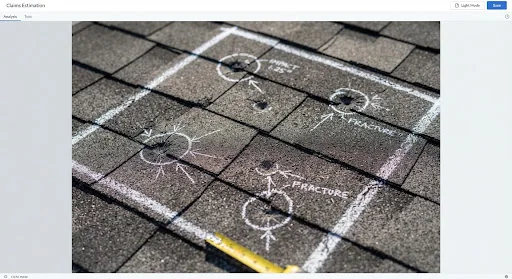
- check_circle Chalk test squares (100 sq.ft test grids per cardinal slope)
- check_circle Macro optical hail gauge caliber calibration & granule loss log
- check_circle Thermal FLIR infrared attic deck moisture scan
- check_circle Sub-centimeter 4K aerial drone photogrammetry & CAD model
- check_circle appropriately qualified inspector presence during independent carrier walk
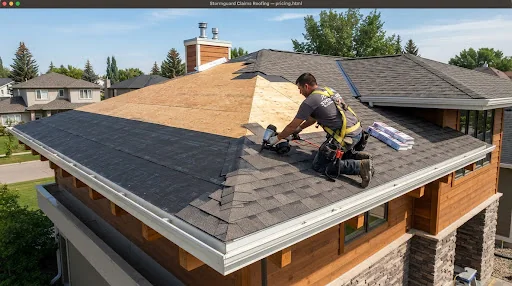
Prairie-Spec Complete Roof Replacement
Built to withstand severe Canadian continental freeze-thaw and 130 km/h gusts.
- check_circle Product specification to confirm
- check_circle Synthetic tear-resistant vapor-permeable underlayment
- check_circle Full 6-foot self-adhering eave ice & water protective membrane
- check_circle Heavy gauge galvanized drip edges and custom valley metal
- check_circle 6-nail high-velocity mechanical fastening pattern
- check_circle 10-year contractor transferable workmanship terms to confirm
What Drives Replacement Square Rates in Southern Manitoba?
Insurance adjusters use localized Xactimate pricing formulas. These four technical factors dictate the variance between standard baseline and complex Prairie roof scopes.
Pitch & Steepness Slope
Standard walkable slopes (4/12 to 6/12) allow standard staging. Steep roofs (8/12 to 12/12) require OSHA/Manitoba fall arrest harnesses, specialized roof jacks, and 25–40% slower install pacing.
Decking & Substrate Plywood
Prairie freeze-thaw and hail puncture can rot sub-sheathing. Degraded 3/8" or 1/2" OSB/plywood must be replaced to ensure manufacturer nail retention warranties.
Valley & Flashing Complexity
Dormers, masonry chimney counterflashing, skylight crickets, and wall kick-outs require hand-formed step flashing and heavy gauge valley metal to prevent winter ice dam backups.
Waste Factor & Facets
A simple gable roof has a 10% scrap waste factor. Intricate multi-hip prairie architecture with 12+ facets generates 15–18% shingle cut waste, included in verified square orders.
Interactive Illustrative CAD Scope Estimator
Simulate standard residential roofing square quantities and investment baselines prior to insurer scope reconciliation.
Honesty Disclosure: Illustrative example only. Independent contractor physical estimate. Insurers independently calculate property depreciation (Actual Cash Value - ACV) and subtract policy deductible.
Request On-Site Verification ScopingFrequently Asked Questions: Prairie Insurance Boundaries
Clear financial distinctions between professional roofing contractors, policyholders, and appropriately qualified insurance carriers.
Can a roofing contractor pay, absorb, or rebate my insurance deductible?
Strictly NO. Under Canadian insurance regulations and Manitoba consumer protection standards, offering to "cover", "waive", or rebate a homeowner's insurance deductible is unlawful and constitutes insurance fraud. The deductible is the legal financial responsibility of the insured homeowner. Contractors who offer deductible rebates often artificially inflate invoices or cut critical installation corners. Stormguard maintains zero-tolerance adherence to ethical scoping.
When do I pay for emergency weather containment and tarping?
Emergency tarping is typically invoiced upon completion of the physical containment work. Most Canadian property insurance policies include a strict clause obligating the homeowner to mitigate further damage immediately following a storm event. Consequently, carrier adjusters generally classify reasonable emergency tarping fees under "mitigation expenses", reimbursing the homeowner directly or paying the contractor directly upon submission of the physical invoice and photographic proof.
What is the distinction between ACV (Actual Cash Value) and RCV (Replacement Cost Value)?
When an insurance carrier approves a roof replacement, they calculate the Replacement Cost Value (RCV), which is the total contractor cost to install a new roof today. However, they first disburse the Actual Cash Value (ACV)—the initial check reflecting the current age and depreciation of your damaged roof, minus your deductible. Once Stormguard finishes the complete installation and submits the final contractor completion certificate, the insurer releases the remaining withheld depreciation (depreciation holdback) directly to you.
Does Stormguard adjust my claim or negotiate financial settlements?
No. Stormguard Claims Roofing is a specialized forensic contractor, not an insurance adjusting firm or legal entity. We provide unassailable physical evidence—such as drone measurements, chalk test squares, shingle manufacturer identification, and wind velocity logs—so that you and your adjuster have accurate data. Final coverage decisions remain between the property owner and the insurer.
Need an exact, uncompromised physical roof scope?
Schedule a mobile scoping team to perform a physical roof deck audit, drone 3D flight, and chalk test before your insurance adjuster walkthrough.